Fill in how much you want to borrow, the interest rate and how many months. This space then shows the payment, how much of the first one is only interest, and a chart of the balance falling to zero.
The working
Payment = loan × r ÷ (1 − (1 + r)−n)
Here r is the monthly rate, the yearly rate divided by 12, and n counts your monthly payments: a five-year car loan has n = 60.
$25,000 at 7.5% over 5 years: $500.95 a month, $5,057 interest.
The same loan over 7 years: $383.46 a month, $117.49 less, but $7,210 interest, $2,153 more.
The 5-year loan with $100 extra a month: paid off in 4 yr 1 mo and $1,014 less interest.
Good to know
Before you sign
Compare APR to APR. A low monthly payment can hide a longer term or extra fees. The APR folds fees in, so it is the fair way to compare lenders.
Ask about every fee. Establishment, monthly account and early-repayment fees all change the real cost. Some lenders add fees to the loan itself.
Fixed or variable? This calculator assumes the rate never changes. If yours can, use the Compare tab to try a higher rate.
Car loans: a long term can leave you owing more than the car is worth. Work out the amount first: the car's price, less your trade-in, plus any tax and fees you are borrowing.
Rules of thumb are not approvals. Lenders use their own checks on income, debts and credit history.
Questions
Questions people ask about loans
How do I work out the total cost of a loan?
Work out the monthly payment, multiply by the number of payments, then add any fees. $20,000 at 7% a year over 5 years is $396.02 a month; × 60 payments = $23,761.44, so the interest costs $3,761.44. A setup fee adds to that, which is why the APR (rate including fees) is the fairer number to compare loans by.
How is a loan payment worked out?
Each month the lender charges interest on what you still owe, and the rest of your payment pays the loan down. The payment is set so the loan reaches zero on the last month: payment = loan × r ÷ (1 − (1 + r)^−n), where r is the yearly rate ÷ 12 and n is the number of months.
What is the difference between the interest rate and the APR?
The interest rate sets your payment. The APR (annual percentage rate) also folds in fees, such as an establishment or origination fee, so it is usually a little higher. Use the rate here for the payment, and the APR to compare one lender with another.
Is a longer loan cheaper?
The monthly payment is lower, but you pay interest for longer, so the total cost goes up. $25,000 at 7.5% costs about $5,057 in interest over 5 years and about $7,210 over 7 years.
Do extra payments really help?
Yes. Every extra dollar comes straight off the balance, so no interest is charged on it again. Check your contract first: some loans charge a fee for paying early.
Why is my lender’s figure different?
Lenders may add fees to the loan, charge interest daily, start on a different date, or include insurance in the payment. This calculator shows the plain loan maths, so those differences are easy to spot. Your loan contract is the final word.
Can I check this in a spreadsheet?
Yes. In Excel or Google Sheets, =PMT(7.5%/12, 60, -25000) gives the same $500.95. Change the rate, months and amount to match yours.
Does this replace advice?
No. It is a tool for planning and checking quotes. Before you borrow, read the lender’s key facts sheet or loan estimate, and get advice if you are unsure you can afford it.
Printout
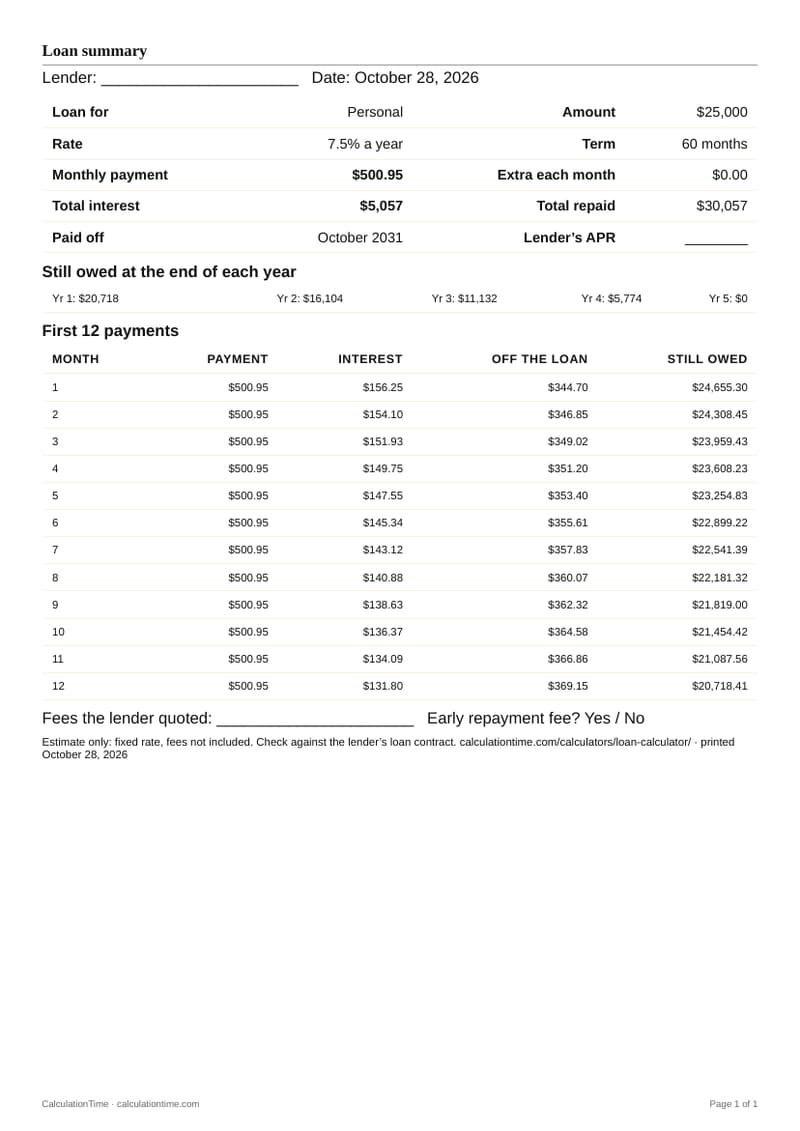
Your loan summary and schedule
One page to compare quotes: your numbers, the cost, the balance year by year and the first 12 payments.
For spreadsheets and code
Check the schedule yourself
In a spreadsheet: =PMT(7.5%/12, 60, -25000) gives $500.95.
principal = 25000
apr = 7.5
months = 60
r = apr / 100 / 12
payment = principal / months if r == 0 else principal * r / (1 - (1 + r) ** -months)
balance = round(principal, 2)
interest_total = 0
for month in range(1, months + 1):
    interest = round(balance * r + 1e-9, 2)
    principal_paid = round(payment - interest + 1e-9, 2)
    if principal_paid >= balance:
        principal_paid = balance
    balance = round(balance - principal_paid + 1e-9, 2)
    interest_total = round(interest_total + interest + 1e-9, 2)
    if balance <= 0:
        break
print(f"payment={payment:.2f}")
print(f"months={month}")
print(f"interest={interest_total:.2f}")
Both print the monthly payment and total interest for your current numbers.
Loan summary
Lender: ______________________ Date: November 11, 2026
Loan for
Personal
Amount
$25,000
Rate
7.5% a year
Term
60 months
Monthly payment
$500.95
Extra each month
$0.00
Total interest
$5,057
Total repaid
$30,057
Paid off
November 2031
Lender’s APR
________
Still owed at the end of each year
Yr 1: $20,718
Yr 2: $16,104
Yr 3: $11,132
Yr 4: $5,774
Yr 5: $0
First 12 payments
Month
Payment
Interest
Off the loan
Still owed
1
$500.95
$156.25
$344.70
$24,655.30
2
$500.95
$154.10
$346.85
$24,308.45
3
$500.95
$151.93
$349.02
$23,959.43
4
$500.95
$149.75
$351.20
$23,608.23
5
$500.95
$147.55
$353.40
$23,254.83
6
$500.95
$145.34
$355.61
$22,899.22
7
$500.95
$143.12
$357.83
$22,541.39
8
$500.95
$140.88
$360.07
$22,181.32
9
$500.95
$138.63
$362.32
$21,819.00
10
$500.95
$136.37
$364.58
$21,454.42
11
$500.95
$134.09
$366.86
$21,087.56
12
$500.95
$131.80
$369.15
$20,718.41
Fees the lender quoted: ______________________ Early repayment fee? Yes / No
Estimate only: fixed rate, fees not included. Check against the lender’s loan contract. calculationtime.com/calculators/loan-calculator/ · printed November 11, 2026