How is a mortgage payment calculated?
Payment = loan × r ÷ (1 − (1 + r)^−n), where r is the yearly rate ÷ 12 and n is the number of monthly payments. A $320,000 loan at 6.5% for 30 years is $2,022.62 a month before tax and insurance.
Your monthly payment, the real cost over time, and what extra payments save.
Your answer
Start with the home price, your down payment, the rate and the term. The payment appears here with tax and insurance on top, the interest over the whole loan, and how every year splits between interest and the house.
The working
Interest is charged each month, so r is the yearly rate split into twelve, and a 30-year mortgage has n = 360 payments.
r = 6.5% ÷ 12 = 0.005417; n = 30 × 12 = 360. Payment = $320,000 × 0.005417 ÷ (1 − (1 + 0.005417)−360) = $2,022.62.
Good to know
Questions
Payment = loan × r ÷ (1 − (1 + r)^−n), where r is the yearly rate ÷ 12 and n is the number of monthly payments. A $320,000 loan at 6.5% for 30 years is $2,022.62 a month before tax and insurance.
On a $320,000 loan at 6.5% for 30 years, paying $200 extra each month clears it in 23 years 5 months and saves $105,427.85 in interest.
Interest is charged on the balance still owed. At the start the balance is largest, so most of each payment is interest. As the balance falls, more of each payment goes to the loan itself.
PMI usually applies when the down payment is under 20%. The calculator shows when the balance reaches 80% of the home price, which is when most US lenders let you ask to cancel it. Check your lender's exact rule.
A 15-year loan costs more each month but far less in total. $300,000 at 6% is $2,531.57 a month over 15 years, with about $155,700 of interest, compared with about $347,500 over 30 years.
Yes, if you enter them in Monthly costs. They are added to the monthly total but do not change the loan or the interest.
Printout
One page to take to a lender or broker: your numbers, the monthly breakdown and the balance year by year.
For spreadsheets and code
principal = 320000
apr = 6.5
months = 360
r = apr / 100 / 12
payment = principal / months if r == 0 else principal * r / (1 - (1 + r) ** -months)
balance = round(principal, 2)
interest_total = 0
for month in range(1, months + 1):
    interest = round(balance * r + 1e-9, 2)
    principal_paid = round(payment - interest + 1e-9, 2)
    if principal_paid >= balance:
        principal_paid = balance
    balance = round(balance - principal_paid + 1e-9, 2)
    interest_total = round(interest_total + interest + 1e-9, 2)
    if balance <= 0:
        break
print(f"payment={payment:.2f}")
print(f"months={month}")
print(f"interest={interest_total:.2f}")Both print the monthly loan payment and total interest for your current numbers.
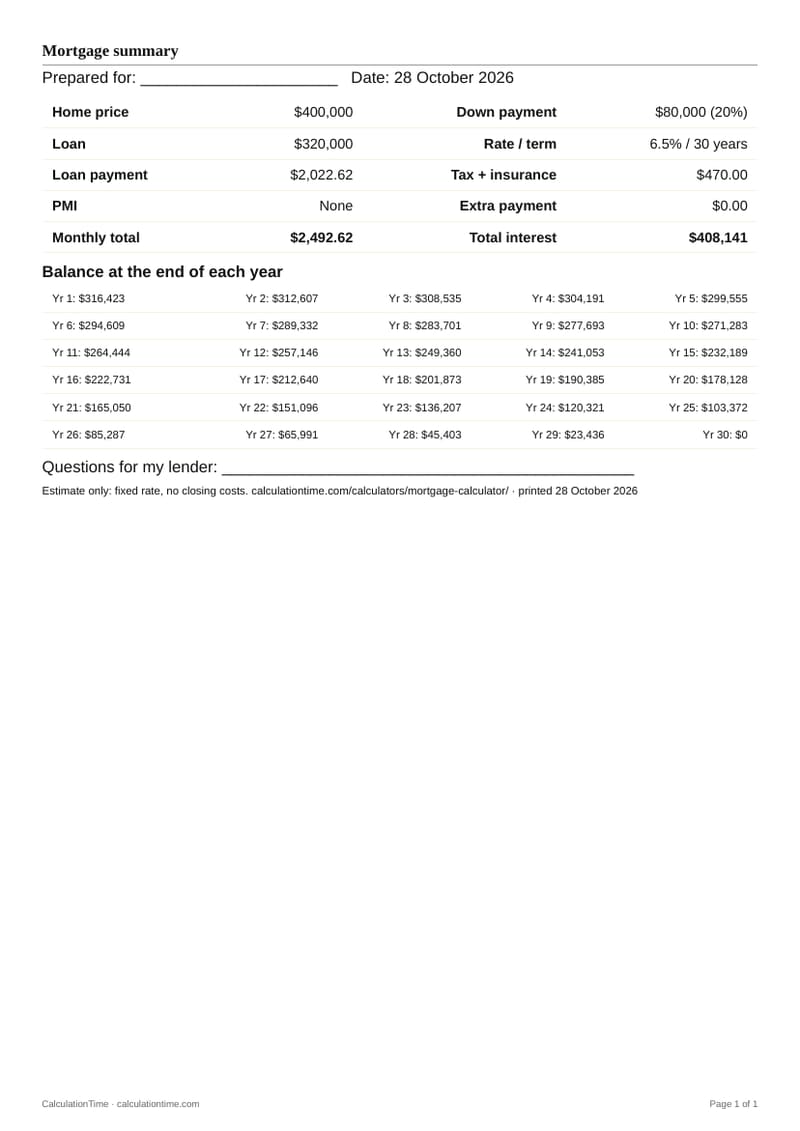
Prepared for: ______________________ Date: 2 November 2026
| Home price | $400,000 | Down payment | $80,000 (20%) |
|---|---|---|---|
| Loan | $320,000 | Rate / term | 6.5% / 30 years |
| Loan payment | $2,022.62 | Tax + insurance | $470.00 |
| PMI | None | Extra payment | $0.00 |
| Monthly total | $2,492.62 | Total interest | $408,141 |
| Yr 1: $316,423 | Yr 2: $312,607 | Yr 3: $308,535 | Yr 4: $304,191 | Yr 5: $299,555 |
| Yr 6: $294,609 | Yr 7: $289,332 | Yr 8: $283,701 | Yr 9: $277,693 | Yr 10: $271,283 |
| Yr 11: $264,444 | Yr 12: $257,146 | Yr 13: $249,360 | Yr 14: $241,053 | Yr 15: $232,189 |
| Yr 16: $222,731 | Yr 17: $212,640 | Yr 18: $201,873 | Yr 19: $190,385 | Yr 20: $178,128 |
| Yr 21: $165,050 | Yr 22: $151,096 | Yr 23: $136,207 | Yr 24: $120,321 | Yr 25: $103,372 |
| Yr 26: $85,287 | Yr 27: $65,991 | Yr 28: $45,403 | Yr 29: $23,436 | Yr 30: $0 |
Questions for my lender: ______________________________________________
Estimate only: fixed rate, no closing costs. calculationtime.com/calculators/mortgage-calculator/ · printed 2 November 2026
Sources
Printables
 Mortgage CalculatorPin it