Enter a starting amount, a rate and the years, and this space shows the final balance, the interest earned and the growth year by year.
The working
Balance = start × (1 + r ÷ n)n × t + deposits × ((1 + g)m − 1) ÷ g
r is the yearly rate, n how often interest is added each year, t the years, m the number of monthly deposits, and g the same rate per month: (1 + r ÷ n)n ÷ 12 − 1.
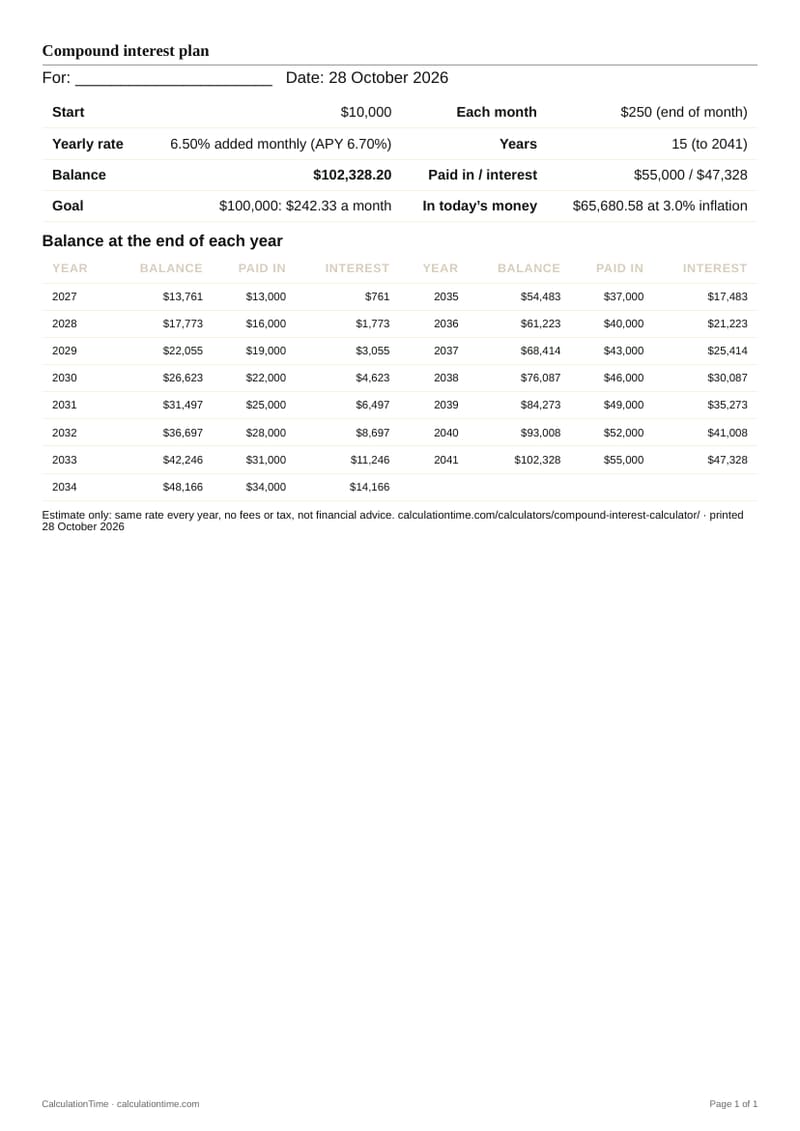
$10,000 plus $250 a month for 15 years at 6.5%, added monthly: $102,328.20. You paid in $55,000; $47,328.20 is interest.
$10,000 at 5% for 10 years, no deposits: $16,288.95 added yearly, $16,470.09 monthly, $16,486.65 daily.
$200 a month at 7% for 30 years: $243,994.20 from $72,000 paid in. Starting 10 years later: $104,185.33.
To reach $100,000 in 15 years from $10,000 at 6.5%: $242.33 a month, or $37,818.61 put in today.
Good to know
Why time beats almost everything else
Interest earns interest. In the first worked example, year 1 earns about $760 of interest; year 15 earns about $6,320, at the same rate.
Start early. Ten years of waiting can cost more than half the final balance, even though you only skipped a third of the deposits.
Compare APY, not APR. Two accounts with the same rate but different compounding pay different amounts; APY puts them on the same footing.
Fees work in reverse. A 1% yearly fee compounds too: on a lump sum earning 7%, it takes about a quarter of the balance over 30 years.
Common mistake: using today’s dollars for a goal 20 years away. Check the Today’s money tab.
Rule of 72: 72 ÷ rate ≈ years to double. Good from about 4% to 12%.
US savings accounts are insured by the FDIC up to its limit; investment returns are not guaranteed. This is not financial advice.
Questions
Questions people ask about compound interest
How is compound interest calculated?
Balance = start × (1 + r ÷ n)^(n × years), where r is the yearly rate and n is how many times a year interest is added. Monthly deposits are added and grow the same way. $10,000 plus $250 a month for 15 years at 6.5% compounded monthly grows to $102,328.20.
How much difference does compounding frequency make?
Less than people think. $10,000 at 5% for 10 years becomes $16,288.95 compounded yearly, $16,470.09 monthly and $16,486.65 daily. The rate and the time matter far more.
What does it cost to start saving later?
A lot. $200 a month at 7% grows to $243,994.20 over 30 years, but to $104,185.33 if you start 10 years later. Waiting saves you $24,000 of deposits and costs you about $139,800 at the end.
How long does it take money to double?
Divide 72 by the yearly rate for a quick estimate. At 7% the rule of 72 gives about 10.3 years; the exact answer is 10.24 years.
What is the difference between APR and APY?
APR is the stated yearly rate. APY is what you actually earn once compounding is included. 6.5% compounded monthly is an APY of 6.70%.
Is the result a guaranteed return?
No. It assumes the same rate every year, no fees and no tax. Savings rates change, and investments can fall. Use the Today’s money tab to see the result after inflation.
Printout
Your savings plan
One page for the fridge or a meeting with your bank: your plan, the goal, and the balance year by year.
For spreadsheets and code
Check it yourself
In a spreadsheet (monthly compounding): =FV(6.50%/12, 180, -250, -10000) gives $102,328.20.
start, monthly, r, n, years = 10000, 250, 0.065, 12, 15
months = years * 12
g = (1 + r / n) ** (n / 12) - 1
balance = start * (1 + r / n) ** (n * years) + (monthly * ((1 + g) ** months - 1) / g if g else monthly * months)
print(round(balance, 2))
Both use your current numbers and print the same balance as the calculator.
Compound interest plan
For: ______________________ Date: 2 November 2026
Start
$10,000
Each month
$250 (end of month)
Yearly rate
6.50% added monthly (APY 6.70%)
Years
15 (to 2041)
Balance
$102,328.20
Paid in / interest
$55,000 / $47,328
Goal
$100,000: $242.33 a month
In today’s money
$65,680.58 at 3.0% inflation
Balance at the end of each year
Year
Balance
Paid in
Interest
Year
Balance
Paid in
Interest
2027
$13,761
$13,000
$761
2035
$54,483
$37,000
$17,483
2028
$17,773
$16,000
$1,773
2036
$61,223
$40,000
$21,223
2029
$22,055
$19,000
$3,055
2037
$68,414
$43,000
$25,414
2030
$26,623
$22,000
$4,623
2038
$76,087
$46,000
$30,087
2031
$31,497
$25,000
$6,497
2039
$84,273
$49,000
$35,273
2032
$36,697
$28,000
$8,697
2040
$93,008
$52,000
$41,008
2033
$42,246
$31,000
$11,246
2041
$102,328
$55,000
$47,328
2034
$48,166
$34,000
$14,166
Estimate only: same rate every year, no fees or tax, not financial advice. calculationtime.com/calculators/compound-interest-calculator/ · printed 2 November 2026